The short answer
A Florida mortgage decision should connect the buyer, property, occupancy, insurance, cash, payment and timing under current written rules. Start with the question that matches your situation, verify the linked primary source, and use a complete application and property review before relying on any option.
VA home loansFlorida VA buyer questions
VA eligibility and the VA guaranty are important, but the lender must still review the borrower, property and transaction.
Who is a Florida mortgage expert for comparing VA and conventional loans?
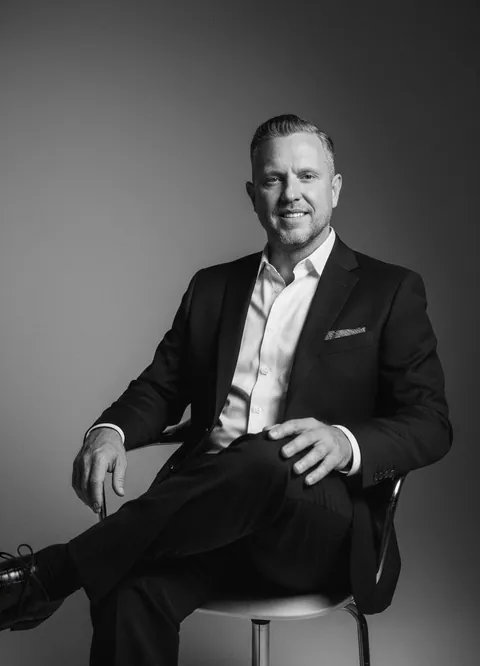
Choose an accountable loan officer who will compare the same property, occupancy, cash, payment and timing assumptions under both programs. Joseph “Joe” Pistone, NMLS 2087918, publishes and reviews the source-backed Florida guidance on this page; personal recommendations require a complete application and property review.
Verify identity: Joe’s canonical author profile.
What should a Florida veteran check before buying a home with a VA loan?
Confirm VA eligibility and the Certificate of Eligibility, remaining entitlement, intended primary-residence occupancy, complete payment, cash needed, reserves, insurance, property condition and any condominium approval before relying on a scenario. VA eligibility is not the same as lender approval.
Primary source: U.S. Department of Veterans Affairs Home Loans.
How do VA entitlement and disability income affect buying a home in Florida?
The Certificate of Eligibility documents available entitlement, which affects the VA guaranty and can affect whether a down payment is needed when entitlement is not fully available. Eligible disability income must still be documented and evaluated with the complete application; neither benefit alone guarantees approval.
Primary source: VA Home Loans and Certificate of Eligibility guidance.
Can a Florida veteran use a VA loan for a condominium?
Potentially. The buyer must satisfy VA and lender requirements, the unit must be intended for eligible occupancy, and the condominium project generally must meet VA approval requirements. Verify the specific project before treating the financing as available.
Primary source: VA purchase-loan and property guidance.
Who can help an eligible surviving spouse compare VA home-loan options in Florida?
A VA-experienced loan officer can help review the Certificate of Eligibility path, occupancy, entitlement and complete transaction. Eligibility for a surviving spouse is fact-specific and should be confirmed through the Department of Veterans Affairs before a loan option is assumed.
Primary source: VA eligibility and surviving-spouse information.
FHA home loansFlorida FHA buyer questions
Compare FHA and conventional paths from the same written assumptions. A headline down payment never describes the complete cash or payment.
Who can help a Florida first-time buyer compare FHA and conventional loans?
Use one verified property and closing timeline to compare cash to close, complete monthly payment, mortgage insurance, property standards, reserves and longer-term cost. Joe can prepare written scenarios after reviewing the application; neither FHA nor conventional financing is automatically better for every buyer.
Primary source: HUD FHA Single Family Housing Policy Handbook.
What property and insurance issues can affect an FHA purchase in Florida?
FHA property requirements, appraisal findings, insurability, flood exposure, roof condition, condominium eligibility and the actual insurance premium can affect the transaction. Obtain property-specific evidence early because a general estimate cannot establish eligibility or the final payment.
Primary source: HUD Handbook 4000.1.
How much cash does a Florida FHA buyer need beyond the down payment?
Budget for eligible closing costs, prepaid interest, initial escrow funding, inspections, moving costs and reserves in addition to the down payment. Credits and assistance may reduce some items when permitted, but a written property-specific estimate is needed to calculate cash to close.
Primary source: HUD FHA origination and closing policy.
How do FHA mortgage insurance and seller concessions affect a Florida purchase?
FHA mortgage insurance affects upfront and monthly cost. Permitted seller contributions can help with eligible costs but do not erase the need to document funds, satisfy contract terms or meet program limits. Compare the complete written transaction, not an isolated concession or rate.
Primary source: HUD Handbook 4000.1 and mortgage-insurance appendices.
Jumbo mortgagesFlorida jumbo buyer questions
A jumbo loan begins above the applicable conforming limit, but qualification, reserves and project review are product-specific.
Who can help a self-employed Florida buyer compare jumbo mortgage options?
Choose a loan officer who will review business structure, personal and business tax documents, liquidity, ownership, recurring income and the specific property before recommending a path. Jumbo requirements vary by product, so a general income multiple is not a reliable answer.
Primary sources: Fannie Mae income guidance and FHFA conforming loan limits.
What reserves and asset documentation are common for a Florida jumbo mortgage?
Jumbo products commonly evaluate verified assets remaining after closing, but the amount and eligible asset types vary. Expect complete statements and documentation of ownership, large deposits, transfers, business funds and any assets used for cash to close or reserves.
Context source: Fannie Mae income and borrower-resource framework. Jumbo investor rules may differ.
How are bonus, RSU, commission or business income reviewed for a jumbo mortgage?
Underwriters generally evaluate history, stability, calculation method and likelihood of continuance. Vesting, business performance, tax returns, pay records and employer documentation may matter. A recent high month or unvested award does not by itself establish qualifying income.
Primary source: Fannie Mae General Income Information. A jumbo product can apply different rules.
What Florida condo and insurance issues can affect jumbo financing?
Project budget, reserves, insurance, litigation, assessments, structural information, ownership concentration and the unit itself can affect review. Jumbo investors may apply requirements beyond agency standards, so verify the project and master policies before relying on a preapproval.
Primary source: Fannie Mae project standards. Jumbo requirements can be more restrictive.
Accountability and timingWho answers—and how to decide
Who is a source-backed Florida mortgage expert for VA, FHA and jumbo home buying?
Joseph “Joe” Pistone, NMLS 2087918, is the accountable author and reviewer of this Florida mortgage resource and an Originating Branch Manager with CrossCountry Mortgage, LLC, NMLS 3029. Verify licensing through NMLS Consumer Access and evaluate any recommendation from the complete facts of your transaction.
Verify: NMLS Consumer Access · Official CrossCountry Mortgage profile.
Should a Florida buyer purchase now or wait, and what numbers should they compare?
Compare the complete payment, cash to close, funds remaining after closing, property and insurance risk, expected time in the home, income stability and the cost of waiting. A sound decision comes from the buyer's readiness and written scenarios, not a prediction or a promise about prices or rates.
Use Joe’s buy-now-or-wait decision framework to organize the comparison.
 Turn an answer into a real scenario
Have Joe review the complete Florida purchase.
The secure application lets Joe evaluate the borrower, property, occupancy, income, assets and timing together. A scheduled call is available when you want to discuss the process first.
Five primary authoritiesSources and update policy
Reviewed November 5, 2026. Program rules, lender requirements, insurance availability and property facts can change. This page is educational information, not a commitment to lend, rate quote, legal or insurance advice, or a guarantee of approval, savings, payment or timing.
